
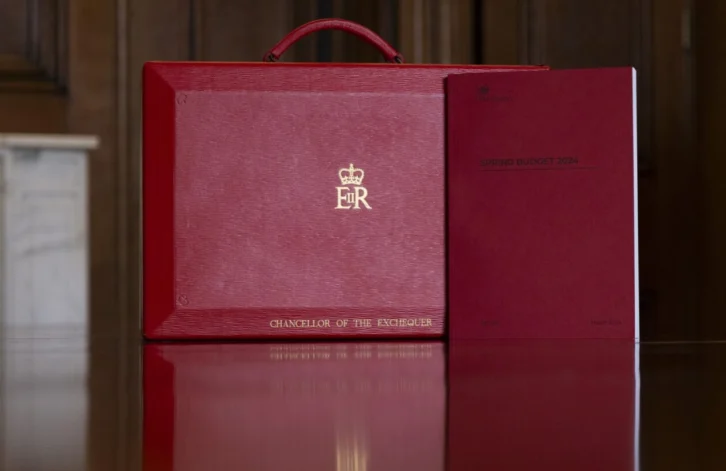
UK technology and business leaders have delivered a mixed response to the Autumn Budget 2026, welcoming commitments to artificial intelligence, startup investment and small business support while raising concerns about gaps in regulation, access to finance and tax simplification.
The Budget included commitments to AI safety and security, measures aimed at supporting founders and growing businesses, and an expansion of Small Business Rate Relief.
However, industry figures warned that investment must be accompanied by clearer guidance, accessible funding programmes and policies that help businesses scale.
UKTN rounds up the reaction from technology entrepreneurs, investors and business leaders.
On the Chancellor’s commitment to ‘backing Britain to lead on AI’
Nik Kairinos, CEO & Co founder, RAIDS AI: “There have been several high-profile reports of AI breaches over the summer, and this heightened attention is prompting many governments to finally take a closer look at the risks posed by AI. It’s encouraging that the UK has committed half a billion pounds to AI safety and security.
“The key will be in how and where that funding is directed. AI is proliferating in many aspects of business, but it’s important that there are clear guidelines in place for businesses, particularly as the roll-out of AI has been so fast that governance has not kept pace. Organisations need support in understanding how they can deploy AI responsibly, by having clear audit trails of what their AI is doing, continuous monitoring to compare AI activity with baseline behaviours, and ensuring that human oversight remains, particularly over autonomous agents.
“The risks from rogue AI to businesses and citizens are significant, but simply not using AI is not an option. This is why organisations need the tools and resources to monitor the potential risks.”
Ritam Gandhi, Director of Studio Graphene, added: “The Budget recognises two things the UK needs to get right: embracing the opportunities AI creates and backing the entrepreneurs who will turn those opportunities into businesses. Measures to support founders and scale-ups are welcome, particularly when building a business takes time, capital and a willingness to take risks. Alongside this, the UK needs to keep investing in AI capability and creating the conditions for businesses to develop and adopt AI in ways that deliver lasting value. Ultimately, the opportunity is to build an environment where ambitious businesses can grow, innovate and compete on the global stage.”
Meanwhile, Tony Kounnis, CEO of Face Int UK, said that amidst the focus on AI, it was a missed opportunity to also invest in facial recognition technology. He commented: “The Chancellor’s failure to recognise facial recognition technology (FRT) in the Autumn Budget is a glaring oversight. Despite some headline commitments to defence and AI, the Government has failed to acknowledge FRT, which harnesses AI to strengthen security.
“While billions are being invested in AI, FRT is already proving its value across the country by helping tackle crime, sure up borders and protect the public. And that’s only half the story; its growing use across the private sector, from care homes and laboratories to gyms and housing complexes, is also helping all manner of businesses strengthen security and get a clearer understanding of exactly who is entering their buildings.
“But FRT, like AI, requires a very careful balance between investment and regulation. There are widespread and understandable concerns among many people about the way images of their faces are captured, stored and used. The Chancellor emphasised the importance of keeping sensitive personal data secure in the UK; this must include the biometric data processed by FRT systems. The Government ought to have used the Budget to announce bolder plans regarding facial recognition, helping to build public trust in the technology and ensuring the tools deployed do not compromise people’s biometric data.”
On access to scale-up capital
Paul Joyce, Partner at LAVA Advisory Partners, a mid-market M&A advisory firm, said: “With so much of this Budget devoted to growth and investment, I do wonder how many owners will come away knowing where to go for the funding that’s supposed to help them expand. You can put a considerable sum behind a scheme and still leave someone running a perfectly good business scratching their head about whether any of it is available to them.
“A clear system for finding and applying for that support deserves as much attention as the amount being allocated. Owners need to understand which options fit their plans and who they should be speaking to, preferably without having to become experts in the Government’s various funding programmes. If we’re hoping they’ll get on with growing their businesses, we should at least make that part of the exercise straightforward.”
On Small Business Rate Relief
Warren Abbey, CEO of 365 Finance, an SME lender, said: “Increasing SBRR was a big win for the private sector, especially SMEs and high street businesses across the country. It will purportedly take 70,000 more companies out of paying business rates, a tax that’s hugely problematic for many small businesses, largely because it’s so rigid. Business rates don’t account for difficult trading conditions – a quiet month, a difficult winter or a period of weak consumer spending do not make the bill any smaller.
“So, it’s positive to see the Government moving towards a tax and policy framework that encourages business growth. Hampering SMEs with significant overheads is illogical; far better to create an environment in which they can scale, hire more people, generate more revenue and lift the entire economy.
“Predictable operating costs are part of the picture, allowing them to think about refurbishing a premises, investing in equipment, increasing stock or taking on staff, rather than constantly protecting cash reserves against the next bill. But more must still be done to boost both business and consumer confidence, allowing owners to plan ahead with greater certainty and be more ambitious in planning for growth.”
On the lack of policies relating to tax simplification
Marco Donzelli, Global CEO of HLB International, the global advisory and accounting network, said: “I had hoped the Chancellor would do something about the extraordinary amount of time companies spend on tax administration. Finance directors could point to multiple examples of unnecessary paperwork, and for businesses operating internationally, the frustrations are compounded by having to reconcile different reporting requirements across several countries.
“I find it disappointing that another Budget has passed without meaningful progress on this, particularly when the Government is advocating for businesses to invest and expand. The UK cannot do much about the tax systems of other countries, although it certainly has the power to make its own easier to navigate. I’d like to see the Treasury commit to a proper timetable for reducing unnecessary reporting, with some measurable targets for the time and money businesses should expect to save.”